
Flexible Funding Options When the Bank Isn’t the Answer
Private, non-bank funding for business owners
…without pressure or obligation
Need Working Capital, a Line of Credit, or Equipment Financing?
I’ll connect you quickly with capable funding partners who can walk you through your options.
Text or call Emily: 1-617-840-8849, 7 days a week, or email Info@BusinessFundingTLC.com
I answer these myself. If I miss you, I’ll get back to you shortly.
Or click the link below to start online.
About
What We Do HEre
My Role is Simple: I listen to your business needs, understand your timeline, and quickly connect you with capable private, non-bank funding partners.
We also share short, plain-English updates on private lending and different topics related to the economy and business through the blog and videos.
Transparency Note: We’re an independent referral partner, not a lender. We may earn a commission if you receive funding through one of our partners.
Partner programs
Working Capital Loans
Business Lines of Credit
Equipment Financing
Term Loans
Merchant Cash Advances
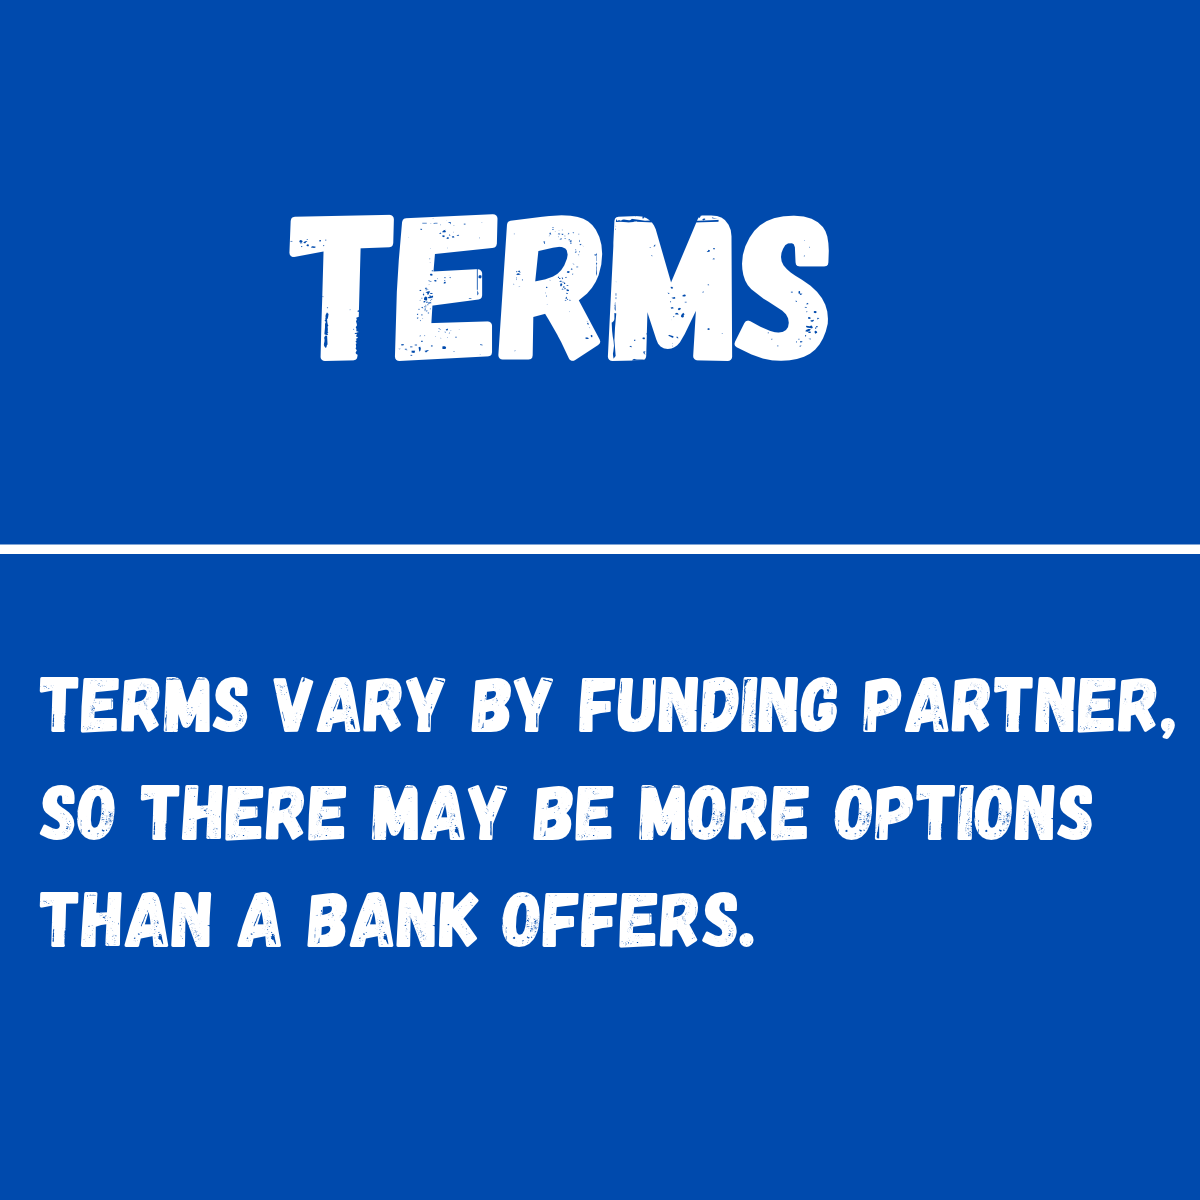
Availability, amounts, terms vary by lender and are subject to approval
Businesses we help
Construction & Trades: Contractors, Roofing, Paving, Excavating, Demolition, Heavy Equipment, Plumbing, HVAC, Electrical, Landscaping
Restaurants, Hospitality & Retail: Restaurants, Bars, Hotels, Motels, Convenience, Grocery, Liquor, Specialty Shops
Professional & Industrial: Healthcare Practices (Medical, Dental, Veterinary, Optometry), Manufacturing, Wholesale Distribution, Auto Repair
And more. Don’t see your industry? Reach out anyway. Text or call me, Emily, at 1-617-840-8849, 7 days a week, and I’ll connect you with the right funding partners..
Why Private Lenders?
HOW THIS WORKS IN 4 STEPS:
Every business is different, so there’s no one-size-fits-all process. Here’s what it typically looks like:
-
-
Description text goes here
-
-
FAQs
How much can I Qualify For?
It depends on your revenue and existing obligations. A funding professional can give you a range after reviewing your situation.
How Fast Can Funding Happen?
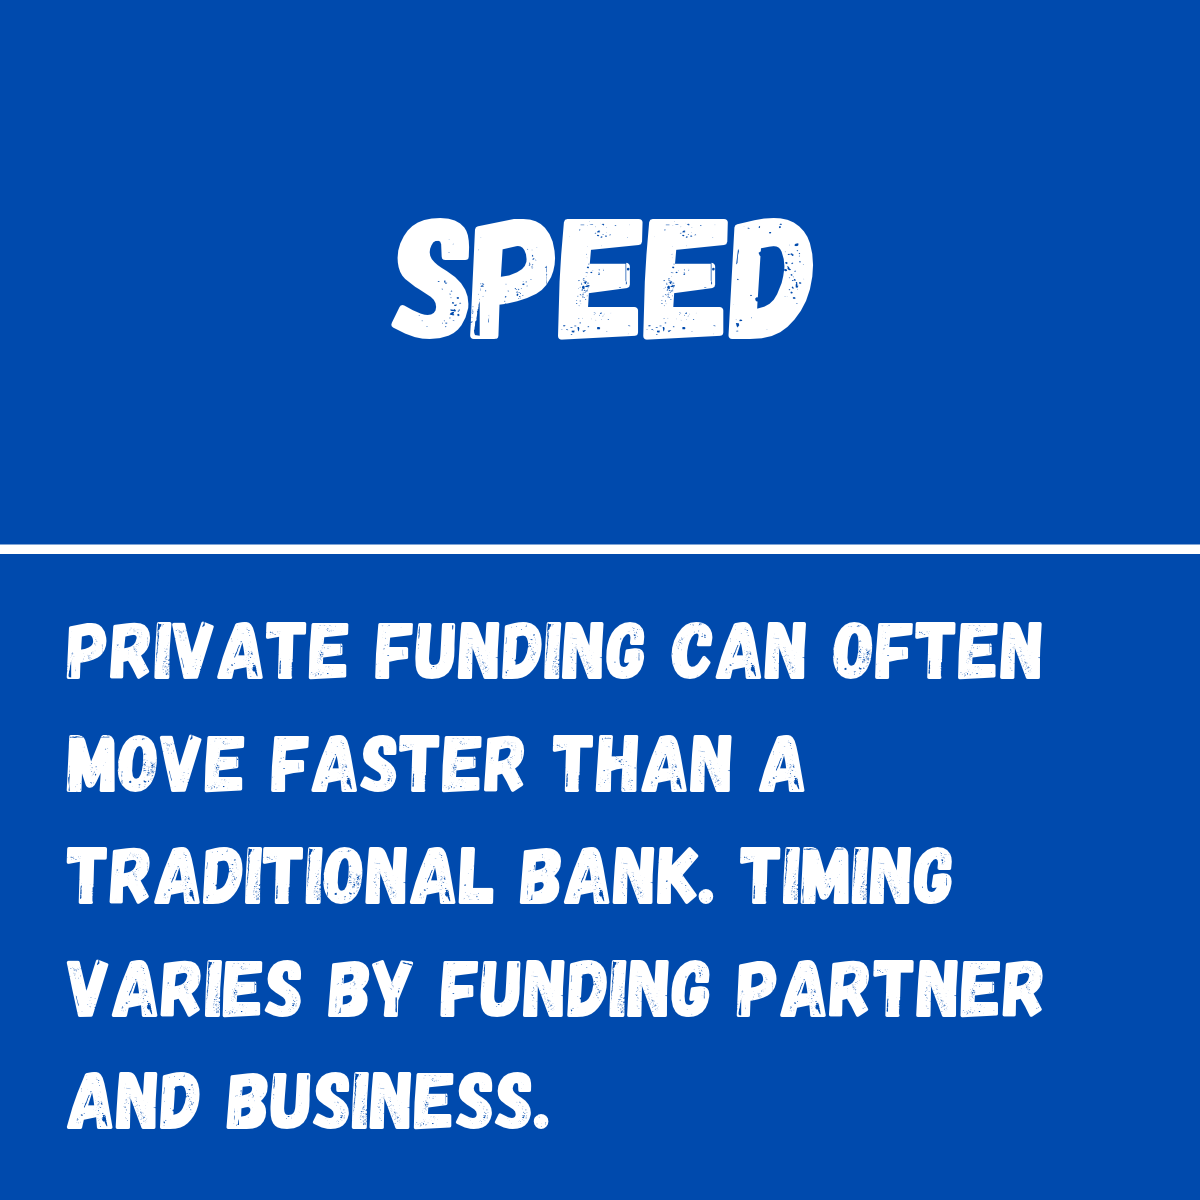
Timing varies by funding partner and by business. Some private funding can move faster than traditional bank loans, depending on the type of funding and how quickly complete documentation is provided.
Do I need Perfect Credit to qualify?
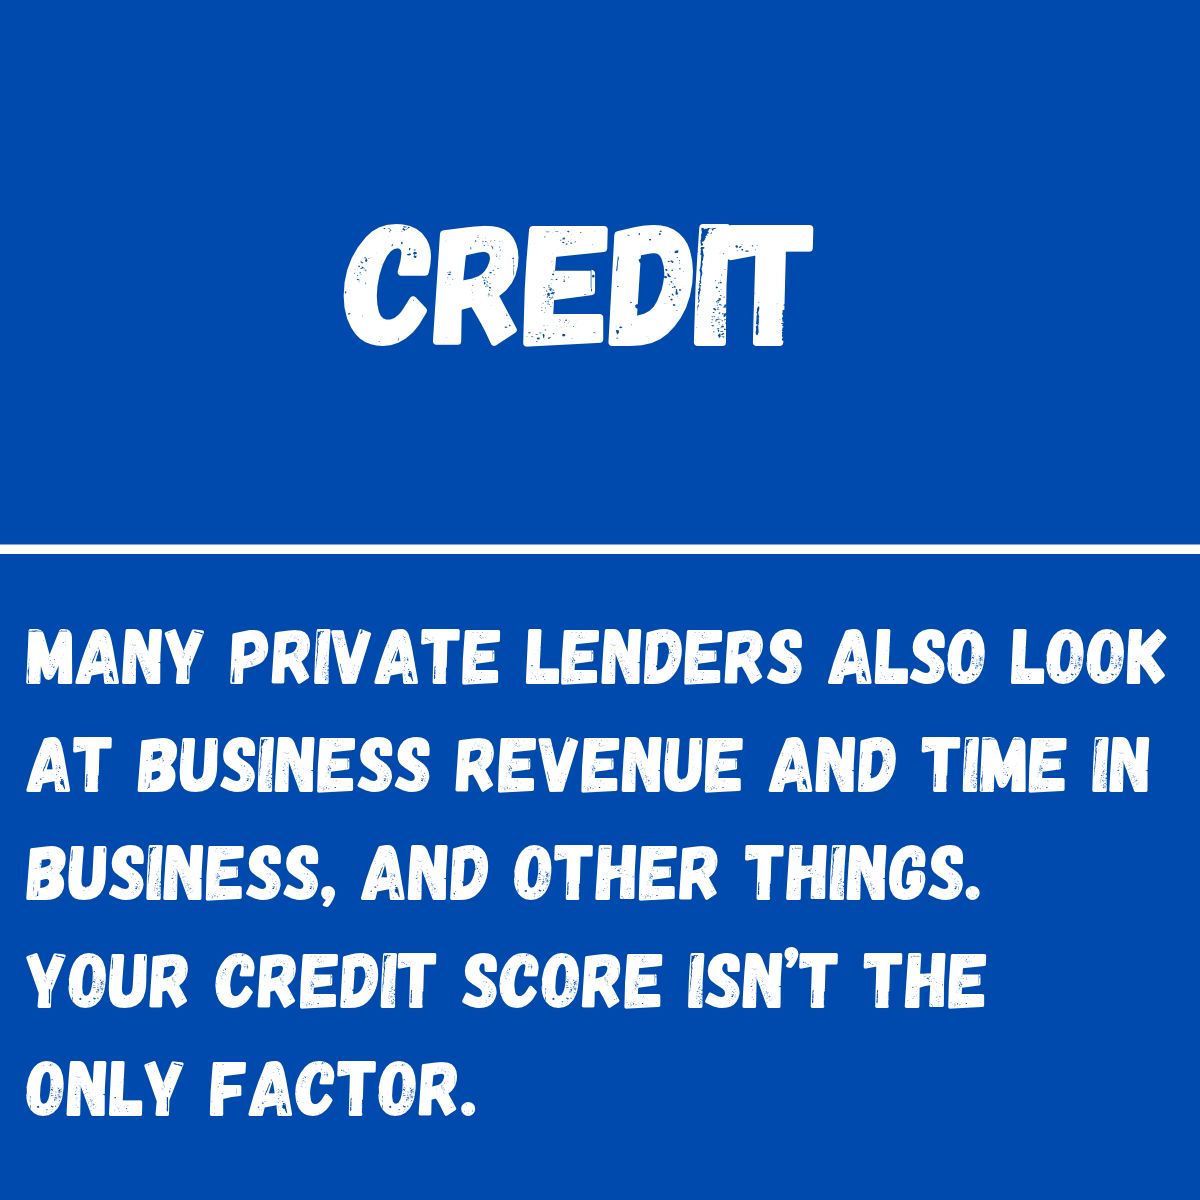
No. Many private lenders focus on business revenue history, time in business, consistency, business model and type of industry — not just your credit score.
Are rates for private lender loans higher than those for bank loans?
Yes, in most cases. Private lender loan rates are typically higher than bank loans due to the increased risks that private lenders accept, and often faster processing times. While they offer speed, flexibility, and access to funds when banks aren't viable, these loans are best considered short-term solutions rather than long-term options.
What if i’ve been declined elsewhere?
This is common. Banks and private lenders use different approval criteria, and private lenders often put more weight on current cash flow and business activity. Approval is never guaranteed.
Is there an obligation to move forward?
No. You are never required to accept an offer just because you spoke to someone or applied.
Looking for Business Funding
or Need More Information?
Text or Call Emily: 1-617-840-8849 - email: info@businessfundingtlc.com - 7 Days a Week
…or, Submit some info:
By submitting this form, or by texting or calling us, you agree that Business Funding TLC and its funding partners may contact you by phone, text, or email about business funding options, including by automated means, at the number and email you provide. Consent isn’t required to get funding. Message frequency varies, and message and data rates may apply. Reply STOP to opt out or HELP for help.
When Banks Tighten, Your Options Matter
November 6, 2026 - Post-midterm volatility has some business owners asking whether to borrow now or wait. A second question matters just as much…if not more: what’s happening to the bank’s willingness to lend?
What the latest data shows
The Federal Reserve’s Senior Loan Officer Opinion Survey (SLOOS) for October found that lending standards for large and medium-sized businesses held up in the third quarter. Smaller firms fared worse. About 5% of banks tightened standards for small businesses, and those borrowers saw stricter collateral requirements and interest rate floors.* In other words, when conditions get uncertain, the squeeze tends to land first on the smallest borrowers.
In practice, tighter bank credit can mean:
Higher credit and cash-flow requirements
More collateral, valued more conservatively
Interest rate floors and wider pricing
Smaller credit lines and shorter terms
Slower approvals and heavier documentation
Strong borrowers can still get approved, but the margin for imperfection shrinks.
Where private, non-bank funding fits
Private lenders operate outside the traditional banking framework. Many focus on the asset, the cash flow, or the opportunity itself rather than rigid, one-size-fits-all underwriting. That can mean faster decisions and more flexible structures when bank credit is narrowing for small businesses. Private capital isn’t immune to volatility, though. Terms and pricing can shift, so compare your options carefully.
Four moves to consider making now
Start early. Talk to lenders before the need is urgent.
Stress-test your numbers. Make sure repayment works in a conservative scenario.
Be careful with market-based collateral. A sharp drop can shrink your borrowing power when you need it most.
Get your documents ready. Financials, tax returns, and a clear use-of-funds plan speed up any approval.
The bottom line: Volatility rewards preparation and options. When traditional lending gets cautious with smaller businesses, a non-bank alternative can keep your plans moving.
Don’t wait for the market to settle. Contact Business Funding TLC today for a no-pressure conversation about non-bank funding solutions built around your goals and timeline.
*Source: Federal Reserve, Senior Loan Officer Opinion Survey on Bank Lending Practices, October 2026.
This post is for general informational purposes only and is not financial, legal, or tax advice. Loan availability, terms, and pricing vary by borrower and lender.